Short answer
Most homeowners policies cover sudden and accidental water damage, like a burst pipe, but not gradual leaks, flooding from outside or, without an endorsement, sewer backup. Document everything, report the claim quickly and start mitigation right away.
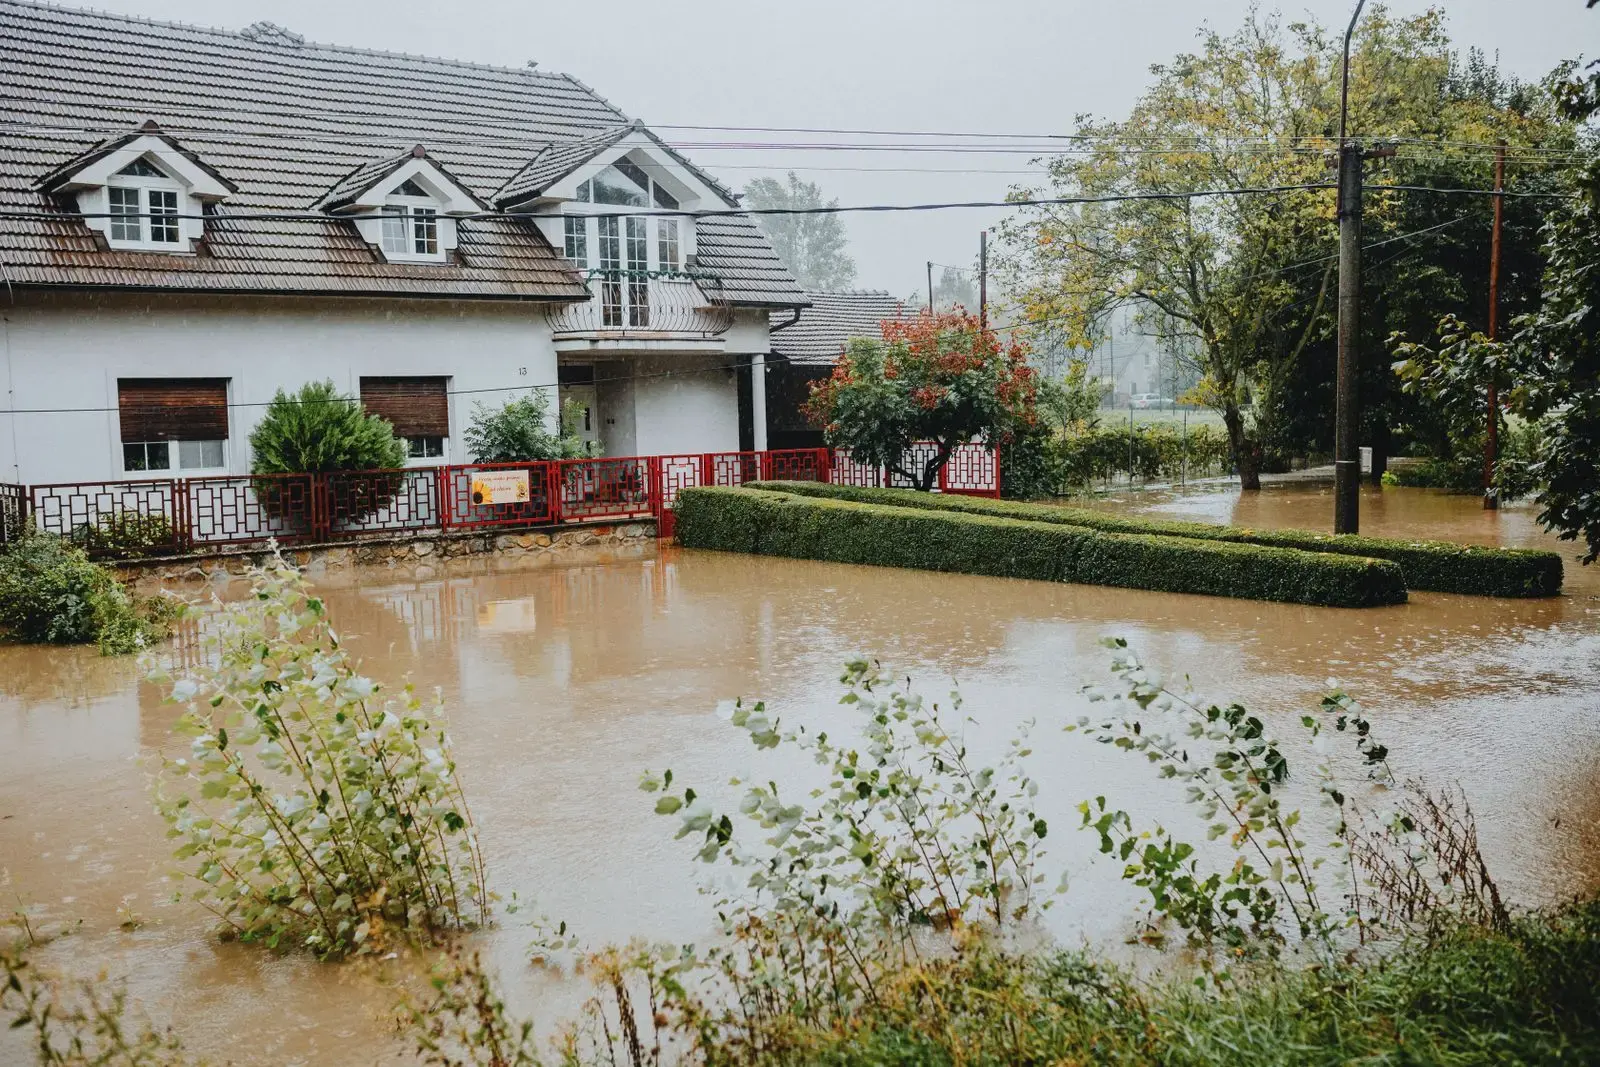
What's usually covered
Coverage varies by policy. Read yours or ask your agent.
- Often covered: burst pipes, sudden appliance failures, water from firefighting
- Often excluded: long-term leaks, groundwater and surface flooding, sewer backup without an endorsement, mold beyond set limits
Documenting the loss
Take photos and video before cleanup, keep damaged items until the adjuster sees them or approves disposal, and save receipts. Ask the restoration company for moisture readings and a drying log.
Working with the adjuster
Ask for an itemized estimate. You can generally choose your own contractor. If you disagree with the estimate, ask the contractor to write up the differences and send them to the adjuster.
Questions
Does homeowners insurance cover flood damage?
Generally no. Flood insurance is a separate policy through NFIP or a private insurer.
Will a water damage claim raise my premium?
It can. Ask your agent how claims affect your rate before filing a small one.
This guide is general information, not professional, legal or insurance advice. Follow your insurer's instructions and local codes, and put safety first.